Posted on

Unlock Your Herne Bay Home’s True Value: Get a Free Property Valuation Today

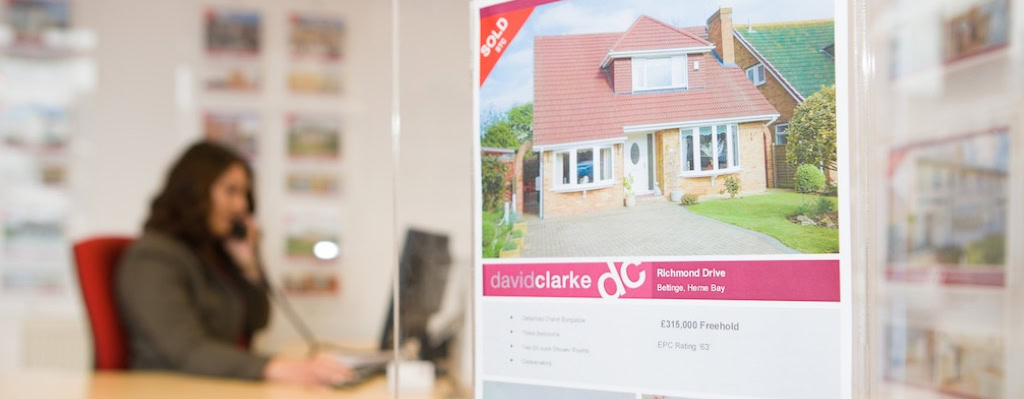
David Clarke Estate Agent in Herne Bay office with a 'SOLD' property advert featuring a house in Richmond Drive, Beltinge.

🏡 Unlock Your Herne Bay Home’s True Value: Get a Free Property Valuation Today

Are you curious about your Herne Bay home’s current market value? Thinking about selling, remortgaging, or simply want to understand the worth of your largest asset? A professional property valuation is the essential first step to making informed decisions.

At David Clarke Estate Agents, we pride ourselves on providing accurate, **free, no-obligation property valuations in Herne Bay** and the surrounding areas. Our expert team combines extensive local knowledge with the latest market data to give you a true picture of your home’s worth.

Ready to find out? Click here to book your free Herne Bay home valuation today!

Why is a Property Valuation So Important in Herne Bay?

Understanding your property’s value goes beyond just selling. Here’s why getting a professional valuation from Herne Bay’s local experts is crucial:

  • Planning to Sell: This is the most common reason. An accurate valuation ensures you set a realistic asking price, attracting serious buyers and potentially achieving a faster sale in the competitive Herne Bay market.
  • Remortgaging or Equity Release: Lenders require an up-to-date valuation to assess your home’s equity, whether you’re looking for better mortgage rates or to release capital.
  • Financial Planning: Your home is likely your biggest asset. Knowing its value is key for long-term financial planning, inheritance, or probate purposes.
  • Avoid Costly Mistakes: Overpricing can lead to your property languishing on the market, while underpricing means you lose out on potential profit. A professional valuation prevents these errors.

What Influences Your Herne Bay Property Valuation?

While online estimates can provide a rough idea, a true valuation considers numerous factors unique to your property and the Herne Bay market. Our valuers look at:

  • Specific Location within Herne Bay: Proximity to the seafront, Herne Bay Pier, schools, local amenities, and transport links (like Herne Bay train station) significantly impact value. Even which street you’re on can make a difference!
  • Property Type & Size: Whether it’s a charming Victorian terrace, a modern detached family home, or a seaside apartment, the square footage and number of bedrooms/bathrooms are key.
  • Condition & Presentation: Recent renovations (new kitchen, bathroom, extensions), general maintenance, and even kerb appeal can add significant value.
  • Local Market Conditions: We constantly monitor supply and demand in Herne Bay, recent comparable sales in your direct neighbourhood, and broader economic trends that affect property prices.
  • Unique Features: Stunning sea views, a large garden, off-street parking, or a garage can all command a premium in Herne Bay.

Our Simple, No-Obligation Valuation Process

Getting your free property valuation with David Clarke Estate Agents is straightforward and stress-free:

  1. Request Your Valuation: Simply fill out our quick online form. You can do that right here.
  2. Local Expert Visit: One of our experienced Herne Bay property specialists will arrange a convenient time to visit your home. This allows us to accurately assess its unique features and condition.
  3. Receive Your Valuation: We’ll provide you with a comprehensive, no-obligation valuation, backed by our deep understanding of the local Herne Bay property market.

Don’t leave your property’s value to guesswork. Gain peace of mind and expert insight from the most trusted **estate agents in Herne Bay**.

Get Your FREE Herne Bay Property Valuation Today!

We’ve been helping people in Herne Bay make confident property decisions for over 50 years. Let our local knowledge work for you.
← Back to all property news & advice

Posted on

How to Choose the Best Estate Agents in Herne Bay

David Clarke estate agents team inside Herne Bay office

🏡 How to Choose the Best Estate Agents in Herne Bay

Looking to buy or sell property in Herne Bay? Choosing the right estate agent is key to a smooth, successful move. With local insight, experience, and personalised service, the right agent makes all the difference. In this guide, we’ll explore what to look for and why David Clarke Estate Agents is a trusted name in Herne Bay.

Choosing the right estate agent is crucial whether you’re looking to sell or to find your perfect house for sale in Herne Bay.

Browse Houses for Sale in Herne Bay

Here are the top five things to consider when choosing an estate agent in Herne Bay:

  • Local Expertise – Choose an agent that truly understands Herne Bay. Street-level knowledge and local data help you price right and sell faster.
  • Track Record – A long-standing history of successful sales builds trust. Look for an agency with real client reviews and proven results.
  • Modern Marketing – High-quality photos, virtual tours, and visibility on Rightmove and OnTheMarket will attract more serious buyers.
  • Clear Communication – Your agent should keep you informed every step of the way. Regular updates and fast responses are essential.
  • Transparent Fees – Fair pricing and a no sale, no fee promise mean you only pay when results are delivered — no surprises.

Whether you’re a first-time buyer, seasoned investor, or looking to sell your family home, choosing experienced estate agents in Herne Bay will save time, stress, and money.

📍 Visit David Clarke Estate Agents — trusted in Herne Bay for over 50 years. Book a free, expert valuation or browse properties for sale today.

We’ve helped thousands of people in Herne Bay make their next move with confidence. Our team combines traditional values with modern marketing to give you the edge in today’s market.

Need personalised advice or ready to get started? Contact our Herne Bay estate agents for a no-pressure consultation.

← Back to all property news & advice

Posted on

How to Sell Your House in Herne Bay: A Local Expert’s Guide

Sell your house in Herne Bay with David Clarke Estate Agents – trusted local experts

🏠 How to Sell Your House in Herne Bay: A Local Expert’s Guide

Thinking about selling your home in Herne Bay? At David Clarke Estate Agents, we’ve helped hundreds of local homeowners make the move with confidence. Whether you’re upsizing, downsizing, or relocating, getting the best result starts with the right advice — and a proven local team. If you’re thinking of selling your current home to find something new, start by browsing our houses for sale in Herne Bay to see your next potential property.

View Houses for Sale in Herne Bay

Here’s our expert guide to selling your house in Herne Bay, covering everything from valuation to completion:

  • Get a Professional Valuation – Every successful sale starts with an accurate market valuation. Our team provides free, no-obligation appraisals based on real-time local data and property insights.
  • Prepare Your Property for Market – First impressions matter. We help sellers present their homes at their best with professional photography, 3D Matterport tours, and staging advice.
  • List Strategically – We’ll market your home across high-traffic portals like Rightmove and OnTheMarket, and leverage local buyer demand via our active database and street-level knowledge.
  • Host Accompanied Viewings – Our agents personally conduct every viewing to build rapport and handle buyer objections on the spot, improving your chances of a strong offer.
  • Negotiate with Experience – We don’t just accept the first offer — we negotiate the best possible outcome, protecting your interests at every stage.
  • Sales Progression Support – Our dedicated team chases solicitors, updates you regularly, and helps manage the full process through to completion, avoiding delays and fall-throughs.

Our no sale, no fee promise means you only pay when your property is successfully sold. There’s no upfront cost or risk — just expert support from a trusted local team.

📍 Sell your house in Herne Bay with David Clarke — book your free valuation today and see what your home is really worth.

We’ve been helping Herne Bay homeowners for over 50 years. With our local knowledge, personal service, and proven results, you can sell with confidence — and peace of mind.

Need tailored advice? Contact our Herne Bay estate agents for a no-obligation chat about your move.

← Back to all property news & advice

Posted on

Landlords: Stay Compliant with Electrical Safety Standards in the Private Rented Sector

Landlords: Stay Compliant with Electrical Safety Standards in the Private Rented Sector 1

⚡ Landlords: Comprehensive Guide to Electrical Safety Standards in the Private Rented Sector

Ensuring the safety of your tenants is not just a moral obligation but a legal requirement. At David Clarke Estate Agents, we assist landlords in Herne Bay and Whitstable to navigate the complexities of property regulations, including the crucial electrical safety standards.

Here’s an in-depth look at the Electrical Safety Standards in the Private Rented Sector (England) Regulations 2020:

  • Mandatory Inspections – Landlords must ensure that electrical installations in their properties are inspected and tested by a qualified person at least every five years, in accordance with the 18th edition of the wiring regulations.
  • Scope of Inspection – This includes all fixed electrical cables and equipment, such as showers or fitted kitchen appliances that are directly connected to the electrical supply.
  • Electrical Installation Condition Report (EICR) – After the inspection, landlords receive an EICR, which outlines the condition of the property’s electrical installations, any required remedial work, and the date for the next inspection.
  • Applicable Tenancies – These regulations apply to all new tenancies from 1 July 2020 and existing tenancies from 1 April 2021. This includes Assured Shorthold Tenancies, Assured Tenancies, Licences to occupy, Secure Tenancies, Regulated Tenancies, Rent Act tenancies, Rent Agriculture tenancies, and Non-Housing Act tenancies.
  • Excluded Tenancies – Examples include social housing, long leases, student halls of residence, hostels and refuges, care homes, hospitals and hospices, and shared accommodation with a landlord or landlord’s family.
  • Renewed Tenancies – A renewed fixed-term tenancy is considered a new tenancy; therefore, from 1 July 2020, all renewed fixed-term tenancies need to adhere to electrical safety standards.
  • Periodic Tenancies – Statutory Periodic tenancies are classed as new tenancies and must comply from 1 July 2020. Contractual Periodic tenancies that commence at the end of the fixed-term are considered the same tenancy, with compliance required by 1 April 2021.
  • Qualified Person – A competent individual who can undertake the inspection, testing, and any remedial work in accordance with the electrical safety standards. Typically, this person will be part of a competent persons scheme, such as NAPIT or NICEIC.
  • Post-Inspection Requirements – Landlords must:
    • Supply a copy of the EICR to each existing tenant within 28 days of the inspection.
    • Provide a copy to any new tenant before they occupy the premises.
    • Supply a copy to any prospective tenant within 28 days of a request.
    • Retain a copy of the report and give it to the qualified person carrying out the next inspection.
    • Provide a copy to the local authority within seven days if requested.
  • Remedial Work – If the EICR identifies any issues, landlords must ensure that remedial work is carried out by a qualified person within 28 days or sooner if specified in the report. Written confirmation of the completed work must be obtained and provided to tenants and the local housing authority.
  • Compliance with Wiring Regulations – Existing installations do not need to comply with the 18th edition of the Wiring Regulations if they are deemed safe. Landlords should consult with their inspector to determine compliance.
  • Validity of Existing Certificates – If an existing certificate was issued more than five years ago, regardless of its stated validity period, it will not be applicable under these regulations. A new EICR must be obtained to ensure compliance.
  • Enforcement and Penalties – Local authorities can impose fines of up to £30,000 for non-compliance. Before imposing a financial penalty, the local authority must serve a Notice of Intent within six months from when the landlord is in breach, outlining the amount, reasons, and right to appeal.

Compliance with these regulations not only ensures tenant safety but also protects landlords from potential legal and financial repercussions.

At David Clarke Estate Agents, our experienced team in Herne Bay and Whitstable is here to provide guidance and support to landlords, ensuring your properties meet all legal requirements.

For expert advice and assistance, contact our estate agents in Herne Bay or estate agents in Whitstable.

Explore more articles on our blog

Posted on

Demystifying Estate Agency Terms: A Guide for Homeowners

Demystifying Estate Agency Terms: A Guide for Homeowners 2

🏡 Demystifying Estate Agency Terms: A Guide for Homeowners

Navigating the property market can be daunting, especially with the myriad of terms used by estate agents. At David Clarke Estate Agents, we believe in empowering our clients in Herne Bay and Whitstable with clear and concise information. We’ve compiled a glossary of essential estate agency terms to help you understand the process better.

  • Agreement in Principle – An estimate of what you could borrow from a mortgage lender based on your income and credit score. Also known as mortgage in principle or mortgage promise.
  • Annual Percentage Rate of Charge (APRC) – A calculation of the overall cost of your mortgage, including interest and fees.
  • Bank Rate – Also known as the base rate, it’s set by the Bank of England and influences other interest rates.
  • Bridging Loan – A short-term loan used to buy a property before selling your current one.
  • Building Survey – A detailed report on the property’s condition, often referred to as a full structural survey.
  • Chain – When multiple transactions are interdependent. A good agent will help keep the chain moving.
  • Commonhold – A form of ownership used in shared buildings, like flats, where each owner owns their property and shares responsibility for the building.
  • Completion Date – The day when ownership transfers to the buyer, and keys are released.
  • Conveyancer – A legal professional who handles the property ownership transfer.
  • Covenant – Legal terms within property deeds that may restrict or require certain actions.
  • Deeds – Legal documents showing who owns the property and outlining any restrictions.
  • Deposit – A sum paid upfront (often 10%) to secure a property purchase.
  • Early Repayment Charge (ERC) – A fee for paying off your mortgage early or switching products during a fixed period.
  • Easement – The legal right to use another’s land for a specific purpose, such as a private path.
  • Energy Performance Certificate (EPC) – Rates a property’s energy efficiency from A to G.
  • Equity – The value of your share in the property, based on market value minus any outstanding mortgage.
  • Exchange of Contracts – The stage where the buyer and seller are legally committed to the sale.
  • Execution-only – Choosing a mortgage deal without receiving advice from a broker or advisor.
  • First-Time Buyer – Someone purchasing a property for the first time.
  • Fixed-rate – A mortgage interest rate that stays the same for a set time period.
  • Freehold – Full ownership of a property and the land it stands on.
  • Gazumping – When a seller accepts a higher offer after previously accepting another.
  • Gazundering – When a buyer lowers their offer at the last moment, pressuring the seller.
  • Interest Rates – The percentage added to the mortgage repayment amount.
  • Land and Building Transaction Tax (Scotland) – A tax applied to property purchases in Scotland.
  • Land Registry – A government record of who owns which land and property.
  • Land Transaction Tax (Wales) – The Welsh equivalent of Stamp Duty, charged on property purchases.
  • Leasehold – Ownership of a property for a fixed period, excluding the land it’s on.
  • Loan-to-Value (LTV) – The ratio between the mortgage loan and the property’s value.
  • Mortgage – A loan to purchase a property, paid back over time with interest.
  • New Build – A property recently built and not previously occupied.
  • Right of Way – A legal right to access or pass through another’s land.
  • Snagging – Fixing minor defects in new builds before the buyer moves in.
  • Solicitor – A legal expert who handles complex property law and transactions.
  • Stamp Duty – A tax paid when buying property or land in England and Northern Ireland.
  • Standard Security (Scotland) – A document confirming that a lender may repossess your home if you default on your mortgage.
  • Standard Variable Rate (SVR) – The default mortgage rate set by lenders after any introductory deal ends.
  • Surveyor – An expert who inspects a property’s structure and identifies issues.
  • Title – The legal right to own a property or land.
  • Under Offer – A property that has had an offer accepted but is not yet sold.
  • Vendor – Another term for the person selling the property.

Understanding these terms can make your property journey smoother and more transparent. Our team at David Clarke Estate Agents is here to guide you every step of the way, ensuring clarity and confidence in your decisions.

For personalised advice and expert assistance, reach out to our estate agents in Herne Bay or estate agents in Whitstable. We’re committed to making your property experience seamless and informed.

Explore more insights on our blog

Posted on

Boost Your Home’s Value Before Selling: Practical Tips for Homeowners

Boost Your Home’s Value Before Selling: Practical Tips for Homeowners 3

🏡 Boost Your Home’s Value Before Selling: Practical Tips for Homeowners

Looking to maximize your property’s value before putting it on the market? At David Clarke Estate Agents, we assist homeowners in Herne Bay and Whitstable with effective strategies to enhance their home’s appeal and achieve the best possible sale price.

Here are some key improvements that can add significant value to your home:

  • Redecorate with Neutral Colours – A fresh coat of paint in neutral tones can make spaces feel larger and more inviting, appealing to a broader range of buyers.
  • Address Minor Repairs – Fixing issues like leaky taps, squeaky doors, or cracked tiles can prevent potential buyers from perceiving the property as neglected.
  • Enhance Curb Appeal – First impressions matter. Ensure your front door is clean or freshly painted, and tidy up the front garden to create an inviting entrance.
  • Upgrade the Kitchen – The kitchen is often a focal point for buyers. Consider updating cabinet doors, replacing countertops, or installing modern fixtures to give it a contemporary look.
  • Modernize the Bathroom – Simple updates like re-grouting tiles, replacing old taps, or adding a new shower curtain can make the bathroom feel fresh and clean.
  • Improve Lighting – Bright, well-lit rooms appear more spacious and welcoming. Use a combination of natural light and artificial lighting to highlight your home’s best features.
  • Declutter and Depersonalize – Removing personal items and excess furniture can help potential buyers envision themselves living in the space.
  • Enhance Outdoor Spaces – A well-maintained garden or patio area can serve as an additional living space, especially during warmer months. Consider adding some potted plants or outdoor seating to showcase this potential.
  • Consider Energy Efficiency – Upgrades like double-glazing windows or installing a smart thermostat can improve your home’s Energy Performance Certificate (EPC) rating, making it more attractive to eco-conscious buyers.
  • Obtain Planning Permission – Even if you don’t plan to extend, having approved planning permission for potential expansions can be a selling point for buyers looking to customize the property in the future.

Implementing these improvements can make your property more appealing to prospective buyers and potentially increase its market value.

At David Clarke Estate Agents, we’re here to provide expert advice tailored to your property’s unique features. Our experienced team in Herne Bay and Whitstable can guide you through the selling process, ensuring you present your home in the best possible light.

For personalized recommendations on enhancing your home’s value before sale, contact our estate agents in Herne Bay or estate agents in Whitstable.

Explore more articles on our blog

Posted on

Tenant Referencing: Ensuring the Right Fit for Your Rental Property

Tenant Referencing: Ensuring the Right Fit for Your Rental Property 4

🔍 Tenant Referencing: Ensuring the Right Fit for Your Rental Property

Selecting the right tenant is crucial for a successful tenancy. At David Clarke Estate Agents, we assist landlords in Herne Bay and Whitstable with thorough tenant referencing to ensure peace of mind.

Tenant referencing involves verifying a prospective tenant’s suitability to rent your property. Key components include:

  • Credit Checks – Assess the tenant’s financial reliability by examining their credit history, including any County Court Judgments (CCJs) or bankruptcies.
  • Employment Verification – Confirm the tenant’s employment status, income, and contract details to ensure they can afford the rent.
  • Previous Landlord References – Gather insights into the tenant’s past rental behavior, including punctuality of rent payments and property upkeep.
  • Right to Rent Checks – Legally required in England, verify that the tenant has the legal right to rent a property in the UK.

It’s important to note that under the Tenant Fees Act 2019, landlords cannot charge tenants for referencing checks. These costs must be borne by the landlord.

If a tenant fails the referencing process, consider:

  • Guarantors – A guarantor agrees to cover rent payments if the tenant defaults. Ensure the guarantor undergoes similar referencing checks.
  • Advance Rent Payments – Requesting additional rent upfront can mitigate potential risks associated with tenants who have limited credit history.

Should you decide not to proceed with a tenant based on their references, any holding deposit taken must be returned within seven days, unless the tenant provided false or misleading information.

At David Clarke Estate Agents, we prioritize finding reliable tenants for your property. Our comprehensive referencing process ensures that your investment is protected.

For expert guidance on tenant referencing and property management, contact our estate agents in Herne Bay or estate agents in Whitstable.

Explore more articles on our blog

Posted on

Gas Safety Checks: Essential Responsibilities for Landlords

Gas Safety Checks: Essential Responsibilities for Landlords 5

🔥 Gas Safety Checks: Essential Responsibilities for Landlords

Ensuring the safety of gas appliances in rental properties is a legal obligation for landlords. At David Clarke Estate Agents, we assist landlords in Herne Bay and Whitstable to stay compliant with gas safety regulations, safeguarding both tenants and investments.

Key responsibilities include:

  • Annual Gas Safety Checks – All gas appliances and flues must be inspected annually by a Gas Safe registered engineer. You can schedule the check up to two months before the current certificate expires without altering the renewal date.
  • Gas Safety Record – Provide tenants with a copy of the Gas Safety Certificate within 28 days of the check or before they move in. Retain copies for at least two years.
  • Maintenance of Pipework – Even if tenants own certain gas appliances, landlords are responsible for the maintenance of associated pipework and ensuring its safety.
  • Pre-Tenancy Checks – Before a new tenancy begins, ensure all gas equipment, including any left by previous tenants, is safe. Repair or remove any unsafe appliances prior to occupancy.
  • Flue Accessibility – For concealed flues, install inspection hatches to allow engineers to assess their condition. Inaccessible flues may lead to appliances being classified as ‘at risk’ and disconnected.
  • Tenant Access – While tenants must grant access for safety checks, if they refuse, document all reasonable attempts to comply with the law, including written communications.

Regular maintenance and prompt attention to gas safety not only fulfill legal requirements but also protect tenants from potential hazards like gas leaks or carbon monoxide poisoning.

At David Clarke Estate Agents, we prioritize the safety and compliance of your rental properties. Our experienced team in Herne Bay and Whitstable is here to guide you through every step of the gas safety process.

For expert advice on gas safety checks and ensuring your property meets all legal standards, contact our estate agents in Herne Bay or estate agents in Whitstable.

Explore more articles on our blog

Posted on

Managing Rent Arrears: A Guide for Landlords

Managing Rent Arrears: A Guide for Landlords 6

💰 Managing Rent Arrears: A Guide for Landlords

Dealing with rent arrears can be challenging for landlords. At David Clarke Estate Agents, we support landlords in Herne Bay and Whitstable to navigate these situations effectively and within legal parameters.

If a tenant misses a rent payment, consider the following steps:

  • Initial Contact – Reach out to the tenant promptly via phone, text, or email to remind them of the missed payment. Maintain a record of all communications.
  • Written Reminder – If there’s no response, send a formal letter or email outlining the arrears and requesting payment.
  • Payment Plan – If the tenant is experiencing financial difficulties, discuss the possibility of a repayment plan to clear the arrears over time.
  • Guarantor Involvement – If a guarantor is listed on the tenancy agreement, inform them of the arrears and request payment.
  • Insurance and Deposit – Check if your landlord insurance covers rent arrears. At tenancy end, you may deduct unpaid rent from the tenant’s deposit, following the scheme’s guidelines.
  • Legal Action – If the tenant accrues two months of arrears without resolution, you can serve a Section 8 Notice under Ground 8. Ensure all communications are documented to support any legal proceedings.

It’s crucial to handle rent arrears with professionalism and adherence to legal procedures. Our team at David Clarke Estate Agents is here to assist landlords in Herne Bay and Whitstable with expert advice and support throughout this process.

For personalized guidance on managing rent arrears, contact our estate agents in Herne Bay or estate agents in Whitstable.

Explore more articles on our blog

Posted on

Landlord Safety Essentials: Smoke Alarms, CO Detectors & Electrical Checks

Landlord Safety Essentials: Smoke Alarms, CO Detectors & Electrical Checks 7

🚨 Landlord Safety Essentials: Smoke Alarms, CO Detectors & Electrical Checks

Ensuring tenant safety is a fundamental responsibility for landlords. At David Clarke Estate Agents, we assist landlords in Herne Bay and Whitstable to comply with safety regulations, safeguarding both tenants and properties.

Here’s an overview of key safety requirements:

  • Smoke Alarms – Install at least one smoke alarm on every storey of the property used as living accommodation. Ensure they are in working order at the start of each tenancy. Failure to comply can result in fines up to £5,000.
  • Carbon Monoxide Alarms – Place a CO alarm in any room with a fixed combustion appliance (excluding gas cookers). Alarms must be operational at the tenancy’s commencement and repaired or replaced if found faulty.
  • Electrical Safety – Conduct Electrical Installation Condition Reports (EICRs) at least every five years. Provide tenants with a copy of the report within 28 days of the inspection. Non-compliance may lead to fines up to £30,000.

Additional safety measures include:

  • Gas Safety – Annual checks by a Gas Safe registered engineer are mandatory for all gas appliances.
  • Legionella Risk Assessment – Assess and mitigate the risk of Legionella bacteria in water systems.
  • Fire Safety – Ensure furnishings meet fire resistance standards, and provide clear escape routes.

At David Clarke Estate Agents, we prioritize safety and compliance. Our team in Herne Bay and Whitstable is dedicated to guiding landlords through their obligations, ensuring peace of mind for all parties involved.

For expert advice on landlord safety requirements, contact our estate agents in Herne Bay or estate agents in Whitstable.

Explore more articles on our blog

Posted on

Understanding Fair Wear and Tear: A Guide for Landlords

Understanding Fair Wear and Tear: A Guide for Landlords 8

🛠️ Understanding Fair Wear and Tear: A Guide for Landlords

When a tenancy ends, it’s common for landlords to expect their property to be returned in the same condition as at the start. However, it’s essential to differentiate between damage and fair wear and tear. At David Clarke Estate Agents, we assist landlords in Herne Bay and Whitstable in understanding these distinctions to ensure fair and lawful handling of tenancy deposits.

Fair wear and tear refers to the natural deterioration of a property and its contents due to normal usage over time. Factors influencing this include the age, quality, and condition of items at the tenancy’s start. For instance, a carpet may show signs of wear after several years of use, which is considered normal.

To assess whether any damage exceeds fair wear and tear, it’s crucial to have a comprehensive inventory check completed and agreed upon with the tenant at the start of the tenancy. This inventory should document the condition of items with photographs, providing a baseline for comparison at the tenancy’s end.

When damage beyond fair wear and tear occurs, landlords must avoid ‘betterment’—improving the property’s condition beyond its original state at the tenant’s expense. Instead, costs should be apportioned appropriately. For example, if a carpet cleaning costs £50 but a new carpet is £500, the tenant may only be responsible for the cleaning cost, not the full replacement.

In cases of severe damage where replacement is necessary, landlords should consider the item’s age and expected lifespan. Apportioning costs based on these factors ensures fairness. For instance, if a five-year-old carpet with a ten-year lifespan is damaged beyond repair, the tenant might be responsible for 50% of the replacement cost.

Maintaining receipts and documentation of item purchases and repairs is vital. This evidence supports any claims made against the tenant’s deposit and aids in resolving disputes.

At David Clarke Estate Agents, we guide landlords through the complexities of property management, ensuring compliance with regulations and fair treatment of tenants. Our team in Herne Bay and Whitstable is here to support you every step of the way.

For expert advice on managing your rental property and understanding fair wear and tear, contact our estate agents in Herne Bay or estate agents in Whitstable.

Explore more articles on our blog

Posted on

What Does a Letting Agent Do for Landlords?

What Does a Letting Agent Do for Landlords? 9

🔑 What Does a Letting Agent Do for Landlords?

Managing a rental property involves numerous responsibilities. At David Clarke Estate Agents, we assist landlords in Herne Bay and Whitstable by offering tailored services to meet their specific needs.

Letting agents typically offer three levels of service:

  • Tenant Find Only – This service includes marketing the property, conducting viewings, vetting potential tenants, carrying out Right to Rent checks, drafting tenancy agreements, and creating an inventory. Once the tenant moves in, the landlord manages the property thereafter.
  • Rent Collection – In addition to finding a tenant, the agent collects rent, manages deposit protection, and addresses rent arrears, providing landlords with financial oversight.
  • Fully Managed – This comprehensive service encompasses all aspects of property management, including maintenance coordination, regular inspections, handling tenant communications, and managing the check-in and check-out processes.

Choosing the appropriate service depends on factors such as the landlord’s proximity to the property, the number of properties owned, and the desired level of involvement.

When selecting a letting agent, consider the following:

  • Tenant Matching – Inquire about the agent’s process for finding suitable tenants and the checks they perform to ensure reliability.
  • Timeframe for Letting – Ask how long it typically takes to let a property in your area.
  • Documentation Provided – Ensure the agent provides all necessary legal documents to tenants at the start of the tenancy.
  • Handling Rent Arrears – Understand the agent’s procedures for managing late payments and regaining possession if necessary.
  • Property Inspections – Confirm how often the agent conducts inspections and how they report findings.
  • Regulatory Compliance – Verify that the agent is a member of a Government-approved redress scheme and has Client Money Protection (CMP) to safeguard your funds.

At David Clarke Estate Agents, we pride ourselves on providing transparent, compliant, and personalized letting services. Our team in Herne Bay and Whitstable is dedicated to ensuring your rental experience is smooth and profitable.

For expert advice and tailored property management solutions, contact our estate agents in Herne Bay or estate agents in Whitstable.

Explore more articles on our blog

Posted on

Understanding Landlord Tax: A Guide for Property Owners

Understanding Landlord Tax: A Guide for Property Owners 10

💼 Understanding Landlord Tax: A Guide for Property Owners

Navigating the tax landscape as a landlord can be complex. At David Clarke Estate Agents, we assist landlords in Herne Bay and Whitstable to comprehend their tax obligations, ensuring they make informed decisions about their property investments.

Whether you’re letting a single property or managing a portfolio, understanding the tax implications is crucial. Here’s an overview of key tax considerations for landlords:

  • Income Tax – Rental income is subject to income tax. Landlords can deduct allowable expenses, such as property maintenance and letting agent fees, to reduce taxable income.
  • Mortgage Interest Relief – Relief on mortgage interest is now restricted to a basic rate tax credit of 20%. This change affects the profitability of buy-to-let investments.
  • Capital Gains Tax (CGT) – When selling a rental property, landlords may be liable for CGT on the profit. The rate and allowances depend on individual circumstances.
  • Furnished Holiday Lettings – Properties meeting specific criteria can qualify for different tax treatment, but changes are forthcoming. From 6 April 2025, the furnished holiday lettings regime will be abolished, aligning their tax treatment with other residential properties.
  • Ownership Structure – Owning property jointly or through a company can impact tax liabilities. It’s essential to choose the structure that aligns with your financial goals.

Additionally, landlords should be aware of the upcoming Making Tax Digital (MTD) initiative. From April 2026, landlords with income over £50,000 will need to comply with MTD for Income Tax Self-Assessment, using compatible software to keep digital records and submit tax returns. Those earning over £30,000 will be included from April 2027.

At David Clarke Estate Agents, we understand the importance of staying informed about tax obligations. Our team in Herne Bay and Whitstable is here to provide guidance and connect you with trusted tax professionals to ensure your property investments remain profitable and compliant.

For personalized advice on managing your rental property’s tax responsibilities, reach out to our estate agents in Herne Bay or estate agents in Whitstable.

Explore more articles on our blog

Posted on

A Landlord’s Checklist: What to Know Before Renting Out Your Property

A Landlord’s Checklist: What to Know Before Renting Out Your Property 11

🏠 A Landlord’s Checklist: What to Know Before Renting Out Your Property

Becoming a landlord is more than just finding a tenant and collecting rent. At David Clarke Estate Agents, we guide property owners in Herne Bay and Whitstable through every step of the letting process, ensuring they meet all legal obligations and make informed decisions.

Whether you’re a first-time landlord or have experience, here are key considerations before renting out your property:

  • Licensing Requirements – Check with your local council to determine if you need a landlord license. In certain areas, operating without one is illegal.
  • Safety Regulations – Ensure your property complies with safety standards, including gas and electrical checks, smoke and carbon monoxide alarms, and energy efficiency ratings.
  • Right to Rent Checks – In England, landlords must verify that tenants have the legal right to reside in the UK.
  • Tenancy Agreements – Provide a written agreement outlining the responsibilities of both parties. In England, also supply the “How to Rent” guide to tenants.
  • Deposit Protection – If taking a deposit, it must be secured in a government-approved tenancy deposit protection scheme within 30 days.
  • Insurance Coverage – Inform your insurer about your intention to let the property. Consider landlord-specific policies that cover buildings, contents, liability, and potential loss of rent.

Additionally, decide whether to let the property furnished or unfurnished, based on your target tenant demographic. Conduct thorough tenant referencing, including credit checks and previous landlord references. Prepare a detailed inventory to document the property’s condition at the start of the tenancy.

Regular property inspections are advisable, but remember to provide tenants with at least 48 hours’ written notice before visiting. Ensure tenants have access to instruction manuals for appliances and know how to operate essential systems like the boiler or alarm.

At David Clarke Estate Agents, we offer comprehensive support to landlords in Herne Bay and Whitstable, from property preparation to tenant sourcing and ongoing management. Our expertise ensures a smooth and compliant letting experience.

Ready to rent out your property? Contact our estate agents in Herne Bay or estate agents in Whitstable for personalized advice and assistance.

Explore more articles on our blog

Posted on

Do You Need House Insurance When Buying a Property?

Do You Need House Insurance When Buying a Property? 12

🏠 Do You Need House Insurance When Buying a Property?

When you’re buying a home, house insurance might not be the first thing on your mind—but it’s an essential step in protecting your investment. At David Clarke Estate Agents, we always advise our clients across Herne Bay and Whitstable to ensure their new property is adequately insured from the moment contracts are exchanged.

There are two main types of house insurance:

  • Buildings insurance – Covers the structure of your home, including walls, roof, windows, and permanent fixtures like fitted kitchens and bathrooms.
  • Contents insurance – Covers the items inside your home such as furniture, electronics, clothing, and valuables.

If you’re buying with a mortgage, your lender will usually require you to have buildings insurance in place from the date of exchange—not completion. This is because you become legally responsible for the property at that point. If something happens between exchange and completion, you could face huge costs without cover.

Contents insurance isn’t mandatory, but it’s highly recommended. Think about the cost of replacing your belongings in the event of a fire, flood, or burglary. Many insurers offer combined policies that cover both buildings and contents for convenience and savings.

When shopping for insurance, compare not only the price but also the coverage. Look at exclusions, excess amounts, and whether the policy includes accidental damage, legal expenses, or alternative accommodation if your home becomes uninhabitable.

Tip: Some providers offer reduced rates if you install a burglar alarm, maintain good locks on windows and doors, or bundle your cover with other insurance types.

At David Clarke Estate Agents, we regularly help clients understand their obligations and connect them with trusted local insurance providers. If you’re unsure what level of cover you need—or when to arrange it—our estate agents in Herne Bay and estate agents in Whitstable are always here to help.

Don’t wait until it’s too late. Ensure you have the right protection in place as part of your home buying journey. It’s one more step towards peace of mind in your new property.

Explore more articles on our blog

Posted on

Choosing the Right Conveyancer or Solicitor for Your Property Sale or Purchase

Choosing the Right Conveyancer or Solicitor for Your Property Sale or Purchase 13

📝 Choosing the Right Conveyancer or Solicitor for Your Property Sale or Purchase

Whether you’re buying or selling a property, selecting the right conveyancer or solicitor is one of the most important decisions you’ll make. At David Clarke Estate Agents, we work closely with both buyers and sellers across Herne Bay and Whitstable to ensure their property transactions are smooth, stress-free, and legally sound.

Conveyancers and solicitors handle the legal side of transferring property ownership. Their role includes reviewing contracts, conducting local authority searches, managing funds, and registering your ownership with the Land Registry. Choosing a professional who is responsive and experienced in residential property law can save you time, money, and frustration.

What’s the difference between a conveyancer and a solicitor?

  • Conveyancer: A licensed specialist in property transactions. They’re often more affordable and highly efficient at handling straightforward sales and purchases.
  • Solicitor: A fully qualified legal professional who can handle more complex legal matters in addition to conveyancing—such as lease extensions or boundary disputes.

Key things to consider when choosing:

  • Experience: Look for someone who deals with your type of transaction regularly—whether freehold, leasehold, first-time buyer, or shared ownership.
  • Communication: Will they keep you updated at each stage? Prompt replies and clarity are essential during the process.
  • Fees: Get a clear breakdown of costs. Some charge fixed fees, while others may work on a sliding scale depending on the sale price.
  • Recommendations: Your estate agent may be able to recommend trusted local professionals based on client feedback and experience.

At David Clarke Estate Agents, we regularly work with a network of reliable conveyancers and solicitors in Herne Bay, Whitstable, and surrounding areas. We’re happy to recommend options that match your budget, urgency, and complexity.

Remember: the cheapest quote isn’t always the best. Paying a little more for someone responsive and thorough can prevent costly delays or legal issues down the line.

Whether you’re upsizing, downsizing, or buying your first home, let our local experts at David Clarke Estate Agents guide you through the legal side of moving with trusted conveyancing partners.

Explore more articles on our blog

Posted on

AML Checks and Proof of Funds: What You Need When Buying Property

AML Checks and Proof of Funds: What You Need When Buying Property 14

🛡️ AML Checks and Proof of Funds: What You Need When Buying Property

If you’re planning to buy or sell a property, be prepared to provide documents for Anti-Money Laundering (AML) checks and proof of funds. It’s a legal requirement that ensures the property market remains a safe, transparent environment for everyone involved. At David Clarke Estate Agents, we take compliance seriously and guide our clients in Herne Bay and Whitstable through this essential step.

Estate agents, mortgage lenders, and solicitors are all required by law to verify the identity of their clients and confirm where their money is coming from. This protects against criminal activity like fraud, tax evasion, and money laundering—and while it might feel intrusive, it’s a normal and necessary part of the process.

What documents will you need to provide?

  • Proof of identity: This includes a valid passport, driving licence, or government-issued ID. It must be current and clear.
  • Proof of address: A recent utility bill, council tax statement, or bank statement (dated within the last 3 months).
  • Proof of funds: You’ll need to show how you’re funding the purchase. This might be savings, proceeds from a previous sale, a gifted deposit, or a mortgage offer.

If you’re receiving help from family or a friend (a gifted deposit), they’ll also need to complete a declaration and provide proof of their own funds. It’s important that all financial sources are traceable and legitimate.

Some buyers wonder why they need to provide these documents more than once. This is because every party in the transaction—your agent, solicitor, and mortgage broker—has a legal duty to carry out their own checks. Fortunately, we make this process as smooth as possible at David Clarke Estate Agents.

Failing to provide the correct documents promptly can delay your purchase. In worst cases, it could even lead to the deal falling through. That’s why we encourage all our clients to get these documents ready early, especially when making an offer on a property.

Our estate agents in Whitstable and Herne Bay are always happy to explain what’s needed, how to prepare, and how your data is handled safely. We treat your information with the utmost confidentiality, complying with the latest GDPR and AML regulations.

Buying a home is an exciting time—and compliance checks shouldn’t get in the way of that. Let David Clarke Estate Agents handle the legalities while you focus on finding the perfect property.

Explore more articles on our blog

Posted on

Understanding Estate Agent Fees: What You’re Really Paying For

Understanding Estate Agent Fees: What You’re Really Paying For 15

💼 Understanding Estate Agent Fees: What You’re Really Paying For

When you’re ready to sell your home, understanding estate agent fees is essential. It’s easy to focus on headline rates, but what you really need to know is what you’re getting in return. At David Clarke Estate Agents, we believe in full transparency and delivering excellent value for every client in Herne Bay, Whitstable, and beyond.

Estate agent fees typically range between 1% and 3% of your home’s final selling price. This might be inclusive of VAT, or VAT might be added separately, so it’s important to check. Some agents charge a flat fee instead of a percentage, particularly with online or hybrid models.

What do estate agent fees cover?

  • Valuation and market appraisal – Setting the right asking price is critical. We base this on in-depth knowledge of the local market.
  • Photography and marketing – Professional photos, floorplans, virtual tours, and promotion on Rightmove, OnTheMarket, and our own website help get your home seen by the right buyers.
  • Accompanied viewings – We manage and host viewings, provide feedback, and follow up with interested parties.
  • Negotiations – We work hard to get you the best possible offer while qualifying buyers for seriousness and financial readiness.
  • Sales progression – After the offer is accepted, we help liaise with solicitors, mortgage lenders, and surveyors to keep the transaction moving.

No sale, no fee. With most high street agents—like David Clarke Estate Agents—you only pay when the sale successfully completes. This model aligns our goals with yours and ensures we’re motivated to get the best result.

Be wary of hidden costs. Some agents advertise low fees but may charge extra for essentials like photos, EPCs, or listings on major portals. Always read the small print and ask for a written breakdown of what’s included.

Choosing the right agent isn’t just about price—it’s about trust, expertise, and local knowledge. Our team of estate agents in Herne Bay and estate agents in Whitstable are known for delivering outstanding customer service and achieving excellent sale prices across the region.

Thinking of selling? Let David Clarke Estate Agents provide a no-obligation valuation and talk you through the process. We’ll explain our fee structure clearly, so you know exactly what to expect—and exactly what you’re getting for your money.

Explore more articles on our blog

Posted on

Buying Property at Auction: What You Should Know

Buying Property at Auction: What You Should Know 16

🔨 Buying Property at Auction: What You Should Know

Buying property at auction can be a fast-paced and exciting way to secure your next home or investment, often at a competitive price. But it’s not without its risks. At David Clarke Estate Agents, our estate agents in Herne Bay and Whitstable regularly support buyers exploring this route, ensuring they’re informed and prepared before placing a bid.

Unlike traditional sales, auctions move quickly. Once the hammer falls, the sale is legally binding and you typically have just 28 days to complete the purchase. That means you need to have your finances, legal checks, and surveyor’s advice all lined up before the auction even begins.

Step 1: Do your research. Study the auction catalogue and shortlist properties that interest you. Request the legal pack for each one—this may include title deeds, lease details, searches, and special conditions. If something doesn’t make sense, a solicitor can help interpret the documentation.

Step 2: View the property in person. Even though timeframes are tight, it’s crucial to inspect the property. Look for structural issues, check the local area, and understand the work (and cost) involved if renovations are needed.

Step 3: Arrange a survey and get a mortgage Agreement in Principle. While some auction properties are cash-buyer only, others are mortgageable—but not all lenders are happy to lend on auction homes. Talk to a mortgage adviser early and make sure your funds can be released in time to meet auction deadlines.

Step 4: Set your budget—and stick to it. Bidding wars can push prices higher than anticipated, so be clear on your ceiling price. Also factor in the buyer’s premium (auctioneer fees), Stamp Duty Land Tax, and legal costs.

Step 5: On the day, be ready to act fast. If your bid wins, you’ll need to pay a 10% deposit immediately and sign the contract. Completion is usually required within 20 to 28 days—miss it, and you could lose both the property and your deposit.

Buying at auction isn’t just for seasoned investors—it’s a growing trend among first-time buyers and downsizers too. But preparation is everything. David Clarke Estate Agents can help you identify suitable auction opportunities in Herne Bay and Whitstable and connect you with professionals who specialise in legal and structural due diligence for auction properties.

Whether you’re after a renovation project, a buy-to-let, or a characterful home you wouldn’t find on the open market, the auction room might hold your next opportunity. With the right support, you can enter confidently and exit successfully.

Explore more articles on our blog

Posted on

Buying the Freehold to Your Flat: What You Need to Know

Buying the Freehold to Your Flat: What You Need to Know 17

🏢 Buying the Freehold to Your Flat: What You Need to Know

If you own a leasehold flat, you may have considered buying the freehold with your neighbours. This process—known as collective enfranchisement—can offer greater control, stability, and long-term financial benefits. At David Clarke Estate Agents, our experienced estate agents in Herne Bay and Whitstable can help you understand the pros, cons, and steps involved.

When you buy a leasehold property, you own it for a fixed number of years, but the land and building are owned by a freeholder. Over time, lease length reduces, which can affect property value and mortgage eligibility. Buying the freehold gives you a stake in the building’s ownership and removes many of the limitations of leasehold living.

Why buy the freehold? It puts leaseholders in control of service charges, building maintenance, ground rents, and future lease extensions. It also removes the risk of dealing with an unresponsive or absent landlord and gives you a permanent say in how your building is managed.

Are you eligible? To qualify, at least half of the leaseholders in the building must participate, and at least two-thirds of the flats must be leasehold with leases originally granted for over 21 years. Houses converted into flats and purpose-built blocks may both qualify, but commercial use must not exceed 25% of the total floor area.

What’s the process? First, leaseholders must formally agree to pursue the purchase together. You’ll then need to instruct a solicitor and a valuation surveyor. The landlord is served with a formal notice, and negotiations begin. The process typically takes several months and legal support is essential throughout.

Costs involved include the freeholder’s valuation, your own legal and surveyor fees, and the purchase price itself. It’s also worth budgeting for building insurance and ongoing maintenance if you become a co-freeholder.

At David Clarke Estate Agents, we often advise leaseholders considering enfranchisement. Whether you’re preparing to extend your lease or buy the freehold, we can connect you with trusted legal and valuation professionals and explain how your decision may affect the marketability and value of your flat.

In competitive areas like Herne Bay and Whitstable, properties with share of freehold often attract more interest from buyers and command a premium. That’s why understanding your options can pay off both now and in the future.

To learn more about leasehold reform or explore flats with share of freehold opportunities, get in touch with the team at David Clarke Estate Agents today.

Explore more articles on our blog